Running a business often means making important investments before the money comes in. You might need working capital to cover payroll, equipment to increase production, inventory for a busy season, or funds to open a new location. The right business loan can help you manage these expenses and pursue growth opportunities.
However, applying without a clear funding plan can lead to delays, expensive borrowing, or rejection. Lenders want to understand how your business earns money, whether it can repay the debt, and how you intend to use the funds.
The smartest approach is to identify your actual funding need, compare suitable financing options, prepare your financial records, and submit a complete application. You may not be able to control a lender’s approval timeline, but you can take steps to make the process more organized and avoid preventable delays.
What Is a Business Loan and How Does It Work?
A business loan provides money that a business agrees to repay according to specified terms. Depending on the product, repayment may involve scheduled principal and interest payments, fees, or other charges. Some loans provide a lump sum for a specific investment, while other financing arrangements offer access to funds as needed.
Businesses commonly use loans for working capital, inventory, equipment, expansion, eligible real estate expenses, or refinancing existing business debt. The amount available, interest rate, repayment period, and collateral requirements depend on the lender and loan program.
In the United States, options may include conventional bank loans, credit union financing, online business loans, and Small Business Administration (SBA)-backed loans.
An SBA-backed loan is provided through a participating lender, not simply handed directly to a business by the SBA. The SBA’s 7(a) loan program supports eligible business purposes, including working capital, equipment, and certain real estate needs.
Before choosing a product, understand what a business loan is and how its repayment obligations fit your business’s cash flow.
How to Apply for a Business Loan
The application process varies by lender and loan type, but these steps can help you prepare and move through it more efficiently.
Calculate how much funding your business needs
Start by identifying the expense the loan will cover. Separate essential costs from optional purchases and estimate how much money is required, when it is needed, and how the investment will benefit the business.
For example, if you need $30,000 for equipment and installation, calculate the complete project cost and subtract any funds you can reasonably contribute. Avoid requesting a much larger loan simply because the lender might offer it. A larger balance can mean higher payments and more interest.
Review your business finances
Before approaching lenders, review your revenue, expenses, outstanding debts, cash reserves, and recent bank statements. Make sure your records tell a consistent story about the business’s financial position.
If revenue varies by season, prepare to explain the pattern. A profitable business can still struggle with repayment if customer payments arrive after major bills are due. Understanding your cash flow helps you estimate a realistic payment amount.
Compare suitable loan options
Research banks, credit unions, reputable online lenders, and relevant SBA-backed programs. Check minimum operating-history requirements, revenue expectations, credit standards, fees, repayment terms, funding timelines, and collateral requirements.
If you need ongoing access to money for short-term cash-flow gaps, a business line of credit may be more suitable than a term loan. If you are purchasing equipment or financing a defined project, a term loan may fit better.
You can compare the differences in business loans and lines of credit before deciding which product matches your needs.
Prepare your application documents
Gather the financial and business records the lender requests before submitting your application. Missing information can lead to follow-up questions and delays.
Requirements differ, so ask the lender for its current document checklist. For SBA 7(a) financing, the application is submitted through a participating lender, and the required documents depend on the loan size and processing method.
Submit a complete application and respond promptly
Provide accurate information about your business, ownership, revenue, existing debts, and intended use of the funds. Review the application for inconsistencies before submitting it.
After submission, monitor your email and phone for lender questions. Responding promptly and providing requested records in an organized format may help avoid unnecessary back-and-forth. However, complete paperwork cannot guarantee approval or a particular funding date.
Review the final offer before accepting
Approval is not the end of the process. Check the interest rate, APR where available, fees, repayment schedule, collateral, personal guarantees, and any restrictions on how you can use the funds.
Make sure the expected business benefit justifies the cost and that payments remain manageable if revenue falls below expectations.
What to Read Next?
What Do You Need to Qualify for a Business Loan?
Business loan eligibility varies by lender and program. A lender generally wants evidence that your business is legitimate, that the requested financing has a clear purpose, and that you have a reasonable way to repay it.
Credit history
Lenders may review business credit, personal credit, or both. A stronger credit profile can improve your options, but approval is not determined by a single score in every case. Review your credit reports for errors and be prepared to explain significant issues.
Revenue and cash flow
Revenue shows how much money your business brings in, while cash flow helps demonstrate whether enough money is available to cover operating expenses and loan payments. Lenders may examine bank statements, financial statements, outstanding debts, and financial projections.
Time in business
Established businesses may have more financial history to demonstrate repayment ability. Startups can face additional challenges because they have limited operating records. A lender may place greater emphasis on a business plan, owner experience, startup capital, and realistic projections.
Business purpose and ownership
Lenders may assess your industry, ownership structure, business location, and intended use of funds. SBA-backed financing has specific eligibility requirements, including rules about business size and eligible activities.
If you need to strengthen your application, read how to improve business loan approval chances and review the full business loan eligibility requirements.
Business Loan Documents: What Should You Prepare?
Preparing documents before applying can reduce delays and help you answer lender questions confidently. The exact checklist depends on the lender, financing product, business age, and requested amount.
Commonly requested documents include:
- Business identification: Legal business name, address, registration details, ownership information, and relevant licenses.
- Bank statements: Recent business account statements showing deposits, expenses, and cash-flow patterns.
- Financial statements: Profit-and-loss statements, balance sheets, and cash-flow information, when available.
- Tax returns: Business and, where required, personal tax returns.
- Business plan: Particularly useful for startups, expansion projects, or applications requiring a detailed explanation of the business strategy.
- Financial projections: Forecast revenue, expenses, and cash available for loan payments.
- Debt information: Existing loans, repayment obligations, and other liabilities.
- Collateral information: Details of assets offered as security, if applicable.
You may also need invoices, purchase quotes, leases, contracts, or a breakdown of how you intend to use the loan. Do not assume every lender requires every document on this list; request the specific checklist for your application.
For a more detailed preparation guide, see business loan documents.
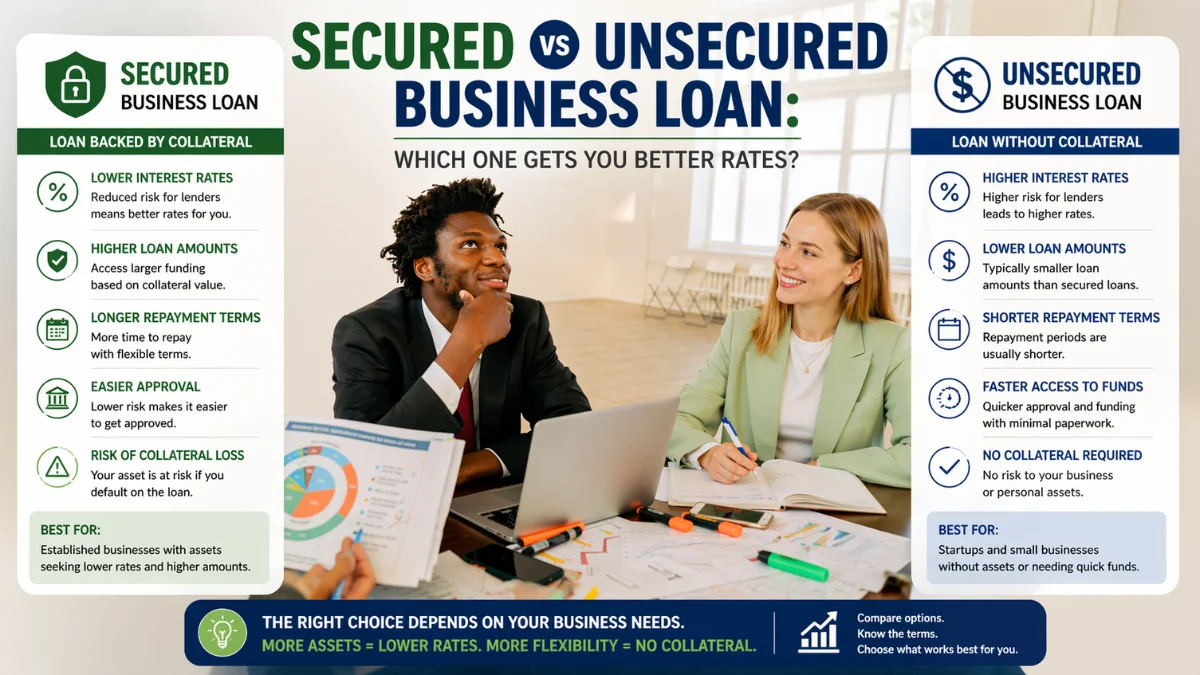
Secured vs. Unsecured Business Loans
One important decision is whether to use collateral to support your borrowing.
| Feature | Secured business loan | Unsecured business loan |
|---|---|---|
| Collateral | Usually requires specified assets | Does not require specific collateral in the same way |
| Approval | Depends on credit, repayment ability, collateral, and lender rules | Depends on credit, cash flow, and lender rules |
| Potential cost | May offer different rates or terms based on risk and security | May carry higher rates or stricter requirements for some borrowers |
| Risk | The lender may enforce its security rights if you default | Default can still lead to collection or legal action |
| Best fit | Businesses with suitable assets and a clear funding need | Businesses seeking financing without pledging specific assets |
An unsecured loan does not mean a loan without risk. Some lenders require a personal guarantee, which can make an owner personally responsible under the guarantee’s terms. A secured loan may put pledged business or personal assets at risk if the debt is not repaid.
Compare the conditions carefully rather than choosing based only on the advertised rate. Read secured vs. unsecured business loans and explore business loans without collateral if you want to understand alternatives.
How to Secure Business Funding Faster
When you need funding quickly, preparation and product selection matter. There is no universal approval or funding timeline, but these steps can help you avoid preventable delays.
Choose the right loan type. Apply for financing designed for your intended use instead of sending the same application to every lender.
- Prepare complete records. Organize statements, tax returns, ownership information, and requested supporting documents.
- Know your numbers. Be ready to explain your revenue, monthly expenses, outstanding debt, and how you will use the money.
- Respond quickly to questions. Check your email and phone and provide accurate follow-up information.
- Compare funding timelines. Ask whether the lender’s stated timeline covers approval, signing, and actual disbursement.
- Review the terms before accepting. Fast access to money is not helpful if repayment costs put the business under pressure.
For eligible U.S. businesses, the SBA’s Lender Match service can connect applicants with potential participating lenders. It is a matching service rather than a loan application or guarantee of approval. You still need to discuss terms and complete the lender’s application.
How Much Business Loan Can You Afford?
The amount a lender is willing to offer may be different from the amount your business can comfortably repay. Estimate a manageable payment before applying.
Start by reviewing your average monthly cash flow after operating costs, payroll, taxes, existing debt payments, and essential reserves. Then consider how much remains available for a new loan payment, including during slower business periods.
You can use the business loan calculator to estimate payments based on the loan amount, interest rate, and repayment term.
For example, suppose a business borrows $50,000 at a hypothetical fixed annual interest rate of 10% and repays it over five years, using equal monthly payments with no additional fees. The estimated payment is about $1,062 per month, and total interest is approximately $13,700 over the full term.
This is an illustration, not a current lender offer. Actual costs can differ because of fees, variable rates, payment frequency, and contract terms. Before accepting a loan, confirm the full repayment schedule and ask whether early repayment charges apply.
Common Business Loan Mistakes to Avoid
A funding decision can affect your business for years. Avoid these common errors:
- Borrowing more than necessary: A larger balance creates additional repayment obligations.
- Ignoring fees: Origination, documentation, servicing, or other charges can raise the effective cost of borrowing.
- Focusing only on speed: A quick offer may have a short repayment schedule or expensive terms.
- Underestimating cash-flow pressure: Payments can become difficult when sales fall or customers pay late.
- Applying without checking eligibility: Review the lender’s requirements before spending time on a full application.
- Overlooking personal guarantees: Understand whether your personal assets or finances could be affected.
- Accepting unclear terms: Get the repayment schedule, fees, collateral conditions, and default provisions in writing.
- Trusting guaranteed-approval promises: Be wary of anyone who guarantees a loan regardless of your circumstances and demands an advance fee in exchange for that promise.
The Federal Trade Commission warns that advance-fee loan scams may promise guaranteed financing in return for upfront payment. Legitimate lenders can charge disclosed application-related fees in some circumstances, but paying a fee does not guarantee that a loan will be approved.
Review business loan mistakes before committing to financing.
What Should You Do If Your Business Loan Is Denied?
A rejection does not necessarily mean your business cannot qualify for financing. Ask the lender what factors influenced the decision and whether it can explain what would make a future application stronger.
Depending on the reason, you might need to reduce existing debt, improve cash-flow records, correct credit-report errors, provide stronger financial projections, request a smaller amount, or consider another suitable lender or loan type.
If the business is new, you may need to strengthen your business plan and demonstrate how the funding will generate enough income to support repayment. Avoid submitting repeated applications without understanding the potential effect of credit inquiries and the reasons for previous rejections.
You should also compare alternatives carefully. A line of credit, equipment financing, or a smaller loan may fit your immediate need better than a large general-purpose loan. The goal is to secure appropriate funding, not simply to obtain an approval at any cost.
Conclusion
Getting a business loan approved and funded quickly starts with knowing exactly how much money you need, choosing an appropriate financing option, and preparing complete financial records. Lenders are more likely to understand your application when you can clearly explain how the funds will be used and how your business expects to repay the debt.
Compare interest rates, fees, repayment terms, collateral requirements, and personal guarantees before signing. If you need U.S. SBA-backed financing, explore eligible programs and participating lenders rather than assuming approval is automatic. Most importantly, borrow an amount your business can reasonably afford, even when a faster or larger offer is available.