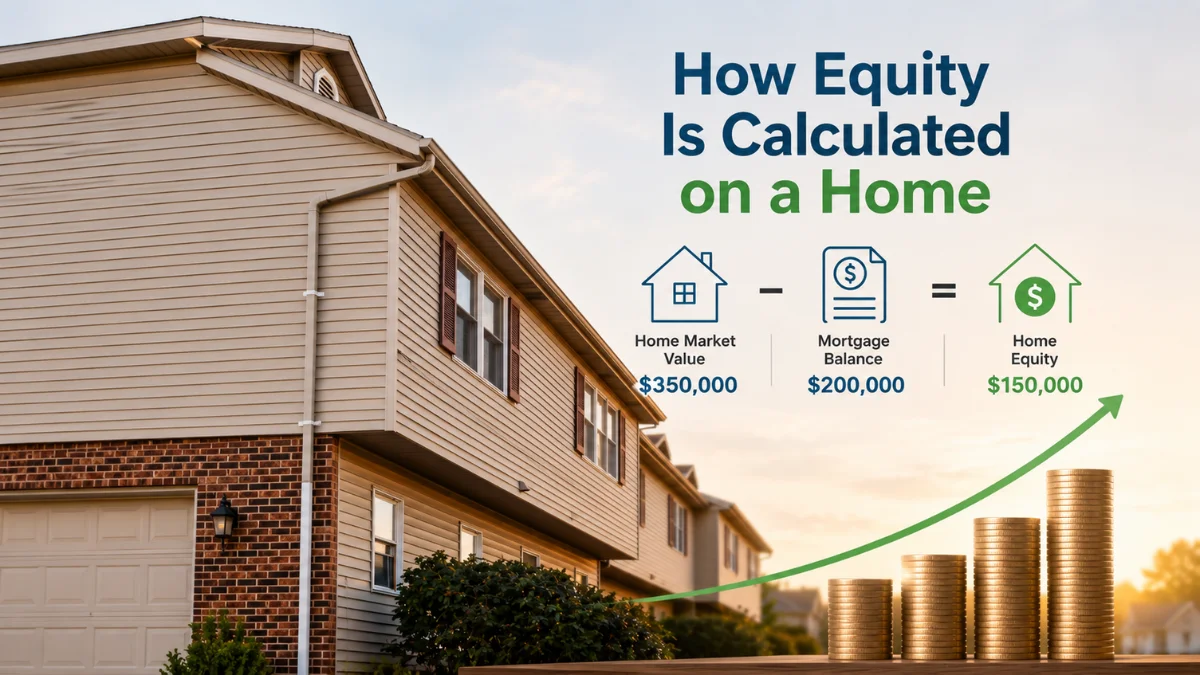
A second mortgage is an additional loan secured by your home while your original mortgage remains in place. Because it is subordinate to the first mortgage, the second lender generally has a lower repayment priority if the property is sold after a serious default. Home equity loans and some other borrowing arrangements can function as second mortgages. You borrow against available equity and make payments according to the terms of the new loan while continuing to make payments on your first mortgage. The additional debt increases your overall housing-related obligations, so affordability is important. You should consider the interest rate, fees, repayment period, and how the additional payment fits into your budget. You can learn more about the differences between these options in our guide to second mortgages vs. refinancing. Using home equity also means your home secures additional debt, which is an important risk to understand before borrowing.