You may have a steady job, a reliable income, and enough money saved for a down payment, yet still worry that your existing debts could stand between you and homeownership.
Perhaps you have student loans, a car payment, credit card balances, or another mortgage. When you add everything together, a large portion of your monthly income may already be committed before you even consider a new house payment.
So, can you still get a mortgage with a high debt-to-income ratio (DTI)? Yes, it may be possible. A high DTI can make qualifying more difficult, but it doesn’t automatically disqualify every borrower.
The outcome depends on the loan program, the lender’s requirements, your overall financial profile, and how comfortably you could manage the proposed mortgage payment.
Understanding how lenders evaluate your debts and what you can do before applying, can help you decide whether to move forward now or strengthen your application first.
What Is Considered a High Debt-to-Income Ratio for a Mortgage?
Your debt-to-income ratio measures how much of your gross monthly income goes toward paying monthly debts, including the mortgage you want to obtain. Lenders use it to assess whether you can reasonably handle another payment alongside your existing financial obligations.
A DTI ratio around 36% or lower is often viewed as a useful target, but it is not a universal mortgage approval requirement. A ratio above 43% may deserve closer attention, while a ratio approaching or exceeding 50% can make qualification more difficult with many lenders. The actual limits depend on the mortgage program, underwriting method, and lender.
For example, Fannie Mae’s published guidelines allow a maximum total DTI of 50% for loans evaluated through its Desktop Underwriter system.
Manually underwritten loans generally have a lower standard limit, with certain borrowers permitted to qualify at higher ratios if they meet additional requirements. These are program-specific guidelines, not a promise of approval. Fannie Mae DTI guidelines explain the distinction.
How Do Lenders Calculate Your DTI Ratio?
Lenders generally calculate DTI by dividing your qualifying monthly debt payments by your gross monthly income, which is your income before taxes and other deductions.
The calculation is:
DTI = Total monthly debt payments / Gross monthly income × 100
Suppose you earn $7,000 per month before taxes. Your expected mortgage payment, including applicable housing expenses, is $2,000, and your other qualifying monthly debt payments total $1,200.
Your total monthly obligations would be $3,200.
$3,200 / $7,000 × 100 = 45.7% DTI
That means approximately 45.7% of your gross monthly income would go toward the debts included in this calculation.
You can estimate your own ratio with the DTI calculator before contacting lenders. For a broader estimate of what you might comfortably afford, the mortgage affordability calculator can also help.
Which debts count toward your DTI?
Depending on your circumstances and the lender’s guidelines, qualifying monthly obligations can include:
- The proposed mortgage payment, including principal and interest, property taxes, homeowners insurance, and applicable mortgage insurance or homeowners association dues.
- Monthly car and other installment loan payments.
- Minimum required credit card payments.
- Student loan payments, including payments calculated under applicable underwriting rules.
- Personal loans and other qualifying recurring debts.
- Court-ordered alimony or child support when applicable under the relevant rules.
Ordinary living expenses such as groceries, electricity, fuel, and entertainment generally are not included as monthly debt payments in the standard DTI calculation.
However, you still need to budget for them because they affect how comfortably you can afford the home.
Can You Get a Mortgage With a 45%, 50%, or Higher DTI?
Your exact ratio matters, but there is no single cutoff that applies to every mortgage application. Here’s how different ratios may affect your options.
Mortgage with a 45% DTI
A 45% DTI may be acceptable under some mortgage programs, provided you meet the applicable credit, income, documentation, and other underwriting requirements.
For example, a borrower with stable employment, a strong credit history, and sufficient savings may present a stronger application than someone with the same DTI but inconsistent income and limited reserves.
Still, approval depends on the complete application. A lender may set a lower limit than the program’s maximum.
Mortgage with a 50% DTI
A 50% DTI is possible under some conventional underwriting pathways, including qualifying loans evaluated through Fannie Mae’s Desktop Underwriter system. Other loan programs and lenders may apply different standards.
At this level, half of your gross monthly income is committed to qualifying debts. That can leave less room for taxes, everyday expenses, home repairs, and unexpected financial setbacks.
Even if a lender approves you, consider whether the payment would leave enough money for your actual household budget.
Mortgage with a DTI above 50%
Getting approved becomes more challenging when your DTI exceeds 50%, but the answer depends on the lender and loan program. Some lenders may decline the application, while others may evaluate whether another eligible loan option is available.
Do not assume that switching to a government-backed loan will automatically solve the problem. FHA, VA, and USDA mortgages have their own eligibility and underwriting requirements, and not every lender accepts the same risk profile.
If your DTI is above 50%, ask a lender to review your complete situation before committing to a home purchase. Reducing your debts or choosing a less expensive property may improve your options.
What to Read Next
What Factors Can Help You Qualify With a High DTI?
A high DTI does not tell the whole story about your finances. Depending on the loan program, lenders may consider other aspects of your application when evaluating your ability to repay the mortgage.
Strong credit history
A history of making payments on time can support your application. Your credit profile may help a lender assess how you have managed previous borrowing, although a strong score does not erase a high DTI or guarantee approval.
If you are preparing to apply, review credit requirements for first-time buyers and check your credit reports for errors before submitting applications.
Stable and verifiable income
Reliable income can help demonstrate that you can manage your proposed payment. Lenders may review pay stubs, tax returns, employment records, or other documents depending on how you earn money.
If you are self-employed or receive variable income, the lender may need additional documentation to determine how much income can be used for qualification.
Savings and financial reserves
Savings can help you handle emergencies and unexpected homeownership expenses. Some underwriting systems may consider available assets or reserves when assessing a higher DTI, but the effect varies by program.
Do not use every dollar of your savings for a down payment simply to improve your application. Closing costs, moving expenses, repairs, and emergency funds also matter.
A manageable proposed mortgage payment
The price of the home you choose can make a substantial difference. A less expensive property may produce a smaller mortgage payment and lower your DTI.
You can compare possible payments using a mortgage payment calculator before deciding how much to borrow.
How Can You Lower Your DTI Before Applying?
If your ratio is too high for the mortgage you want, you may have several ways to improve it. You do not necessarily need to eliminate every debt before buying a home.
Pay down debts strategically
Start by listing your debts, minimum payments, balances, and interest rates. Paying off a debt that removes a substantial monthly payment may improve your DTI more quickly than making a small extra payment toward a debt that still requires the same monthly installment.
Be careful not to drain your emergency savings or miss other payments while trying to qualify.
Reduce credit card balances
High credit card balances can affect your credit profile, and the required monthly payments may contribute to your DTI. Reducing balances can help, although the precise effect depends on the payment amount used in the lender’s calculation.
Avoid taking on new credit card purchases or loans while preparing your mortgage application.
Increase your qualifying income
A documented raise, additional qualifying employment income, or eligible recurring income may improve your DTI. However, lenders must follow their rules for verifying and calculating income.
Do not assume that occasional overtime, a recent side job, or projected future earnings will automatically count. Ask the lender what documentation is required.
Consider a less expensive home
If the proposed mortgage payment is the main reason your ratio is high, reducing your target purchase price may be one of the most direct solutions.
A larger down payment can reduce the loan amount and potentially the monthly payment, but it also reduces your available cash. Compare the payment savings against the money you would have left after closing.
Avoid taking on new debt
A new car loan, personal loan, or large credit purchase can increase your monthly obligations. Even after receiving pre-approval, new debt may affect your final qualification.
Before making a significant financial change, discuss it with your lender.
Review your mortgage options
Different loan programs and lenders may evaluate applications differently. Ask about conventional, FHA, VA, or USDA options only when you meet the relevant eligibility requirements.
For example, eligible veterans may want to explore VA home loan options, while eligible buyers considering a USDA loan can review the USDA home loan calculator.
Compare the full cost of each option, including interest, mortgage insurance where applicable, fees, and long-term affordability—not just the DTI threshold.
Should You Apply for a Mortgage or Wait Until Your DTI Improves?
The right decision depends on both your eligibility and your financial comfort.
Applying now may make sense if your DTI is within a lender’s acceptable range, your income is stable, you have adequate savings, and the proposed payment leaves room for ordinary living expenses and unexpected costs.
Waiting may be worth considering if your current debts consume most of your income, your savings are limited, or the proposed payment would make it difficult to cover repairs and other household bills.
You can start by calculating your DTI, estimating the full housing payment, and reviewing your debts. Then speak with more than one lender to understand the loan options available to you.
Compare written Loan Estimates when you reach that stage, paying attention to the interest rate, fees, mortgage insurance, and total monthly payment.
Remember that pre-approval is not a final guarantee. Lenders may reassess your finances, documentation, and the property before approving the loan.
Frequently Asked Questions
Conclusion
Getting a mortgage with a high debt-to-income ratio is possible in some circumstances, but the outcome depends on the loan program, lender requirements, and your overall financial position.
A ratio near or above 50% deserves careful attention because it can limit your options and leave less room in your budget.
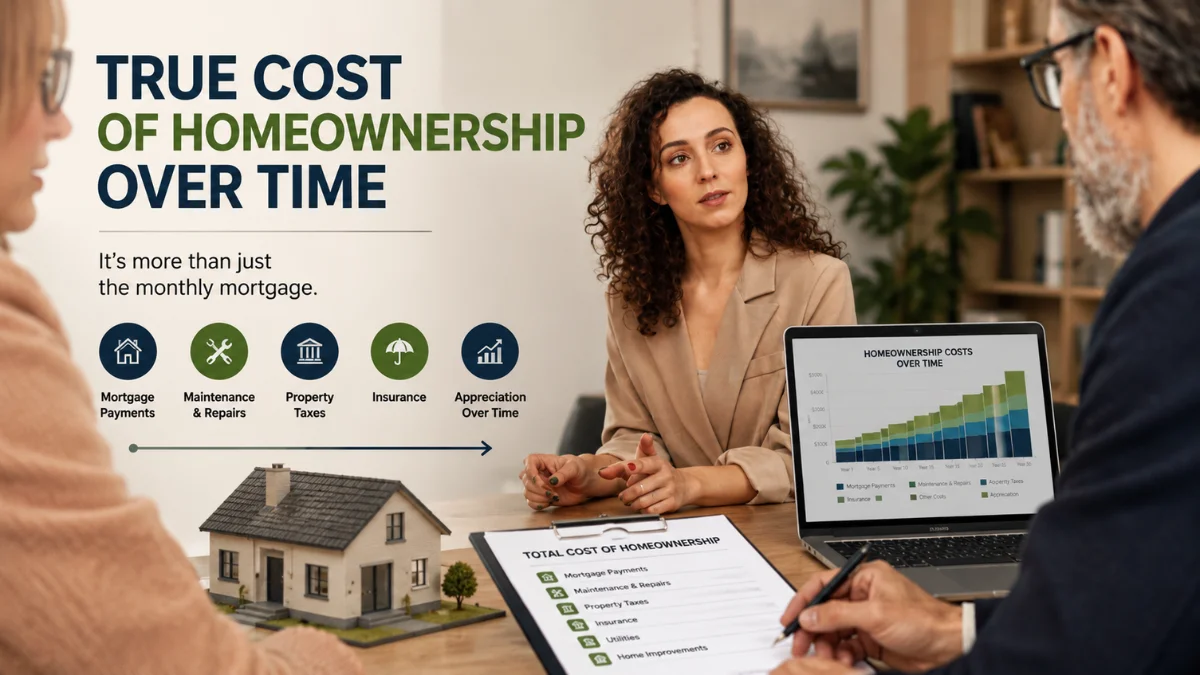
Start by calculating your DTI, checking your credit, and estimating the full cost of homeownership. If the numbers are tight, consider reducing monthly debt payments or choosing a less expensive property before applying.
The goal is not simply to qualify for a mortgage; it is to choose a home loan you can manage comfortably over time.