
Paying high interest on a personal loan can quietly drain your finances over time.
The good news is, you can legally reduce your interest cost with the right strategies.
This guide shows practical ways to lower your total repayment and save money.
Why Personal Loan Interest Becomes Expensive
Many borrowers focus only on EMI and ignore the total interest they pay over the loan period.
A longer tenure or higher interest rate can significantly increase your overall cost.
Interest is calculated on the remaining loan balance, which means the longer you take to repay, the more you pay.
Understanding how personal loans work in real scenarios helps you see why reducing interest early is so important.
Make Extra Payments to Reduce Interest Faster
One of the most effective ways to reduce interest is by making extra payments toward your loan. Even small additional amounts can lower your principal faster.
Since interest is calculated on the remaining balance, reducing your principal early cuts down future interest.
This strategy aligns with smart repayment planning, where consistent extra payments can save a significant amount over time.
Choose a Shorter Loan Tenure
A shorter loan tenure increases your monthly EMI but reduces your total interest cost.
This is because you are paying off the loan faster, leaving less time for interest to accumulate.
If your budget allows, choosing a shorter tenure can lead to substantial savings.
Using tools to understand your monthly payment structure can help you find the right balance between affordability and cost.
Improve Your Credit Score for Better Rates
Your credit score directly affects the interest rate you receive. A higher score signals lower risk to lenders, which can result in better loan terms.
If you improve your credit score before applying or even after taking a loan—you may be able to refinance at a lower rate.
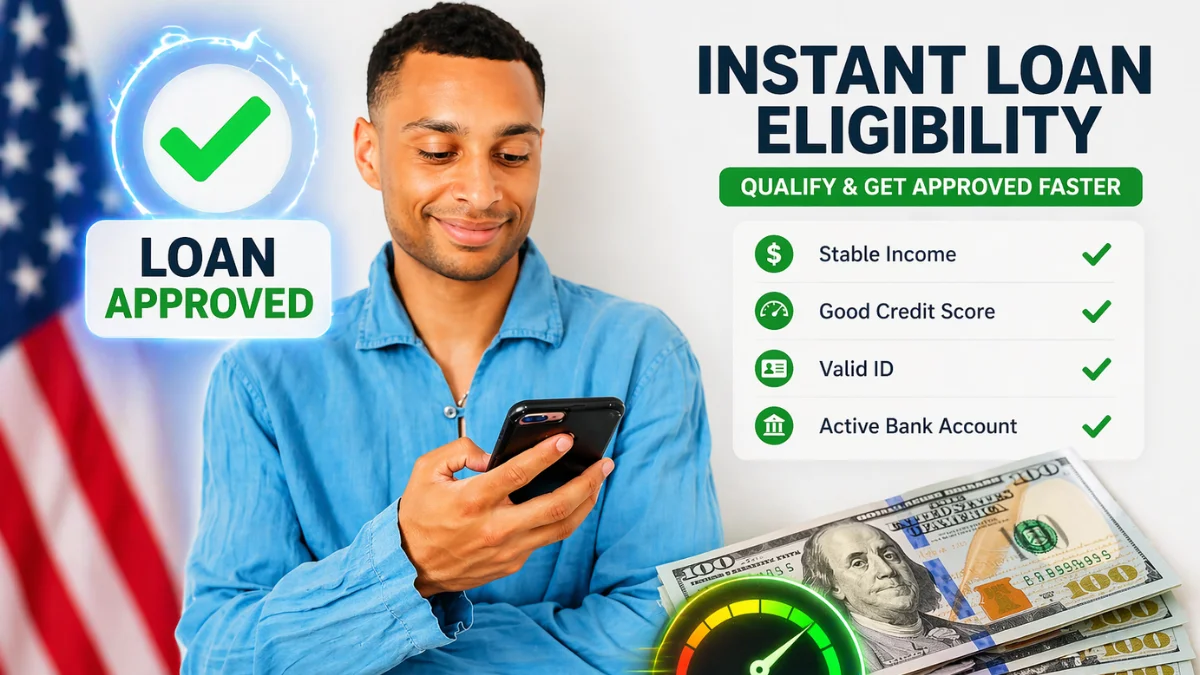
Learning about loan eligibility factors can help you understand how your credit profile impacts interest rates.
Refinance Your Loan at a Lower Interest Rate
Refinancing means replacing your existing loan with a new one that has better terms.
If market rates have dropped or your credit score has improved, refinancing can reduce your interest cost.
However, it’s important to check for processing fees and compare total savings before making a decision.
What to Read Next
Negotiate with Your Lender
Many borrowers don’t realize that interest rates can sometimes be negotiated.
If you have a good repayment history or improved financial profile, your lender may offer a lower rate.
This is especially useful if you have been making timely payments and maintaining a strong financial record.
Avoid Common Mistakes That Increase Interest
Certain mistakes can increase your interest burden without you realizing it.
These include choosing long tenures, missing payments, or not comparing lenders before applying.
Understanding common borrowing mistakes can help you avoid these issues and keep your loan cost under control.
Consider Secured Loan Options
If you’re open to providing collateral, secured loans often come with lower interest rates compared to unsecured loans.
While this reduces your interest cost, it also involves risk since your asset is tied to the loan.
Understanding secured vs unsecured loan differences can help you decide if this option is right for you.
Plan Your Loan Before Applying
Reducing interest starts even before you take the loan. Choosing the right loan amount, tenure, and lender can significantly impact your total cost.
Using a calculator to test different scenarios helps you make smarter decisions.
When combined with a deeper understanding of how personal loans really work and how to pay less interest, this approach becomes even more effective.
Why Reducing Interest Matters
Lowering your interest doesn’t just save money, it improves your overall financial health. It reduces your debt burden, frees up cash flow, and helps you achieve financial goals faster.
A well-planned loan with reduced interest can make a significant difference in your long-term financial stability.
Frequently Asked Questions
Conclusion
Reducing personal loan interest is not just possible, it’s essential for saving money and managing your finances effectively.
With the right strategies, you can significantly lower your loan cost and repay faster.
Before taking or managing a loan, always focus on planning, repayment strategy, and cost optimization.
For a complete understanding of borrowing, approval strategies, and smart financial decisions, explore the full guide on personal loan strategies and smart financial planning to stay in control of your finances.


About Us
We're MortgageRatesChecker, a financial education and tools platform helping consumers make smarter decisions about borrowing, budgeting, saving, and everyday spending. We provide practical guides, calculators, and resources covering mortgages, loans, home buying, refinancing, personal finance, money management, and budget-conscious travel. Explore our guides, calculators, and resources to make more informed financial decisions.
Disclaimer
MortgageRatesChecker provides educational mortgage calculators, loan tools, and financial guides designed to help you better understand home financing. Our content is researched, fact-checked, and regularly updated in accordance with our Editorial Policy, using trusted information from our Data Sources and transparent methodologies explained in How We Calculate. Learn more about our commitment to accuracy on Why Trust Us. This content is provided for informational purposes only and should not be considered financial, legal, tax, investment, or mortgage advice. Mortgage rates, lending requirements, loan programs, and regulations may change without notice. Before making any borrowing, refinancing, or home-buying decision, consult your Bank or Mortgage Lender, licensed financial advisor, tax professional, or attorney based on your individual circumstances. MortgageRatesChecker is an independent educational resource and is not a lender, mortgage broker, financial advisor, or government agency. Please review our Affiliate Disclosure, Advertiser Disclosure, Disclaimer, and Terms & Conditions for additional information.


