A noticeable shift in today’s housing market is that buyers are taking fewer mortgage risks than in previous years.
Instead of stretching finances to secure larger homes or relying on optimistic income projections, many borrowers are choosing safer, more predictable loan structures.
One of the biggest reasons behind this change is rate awareness. Buyers closely monitor mortgage rates today because they understand how quickly borrowing costs can affect long-term repayment totals.
Rather than locking in loans at the edge of their affordability range, households are building financial cushions into their decisions.
Another important factor is conservative budgeting. Instead of borrowing the maximum amount a lender approves, buyers increasingly calculate what feels manageable using a mortgage affordability calculator.
The goal is to ensure monthly payments remain comfortable even if living expenses rise or income fluctuates.
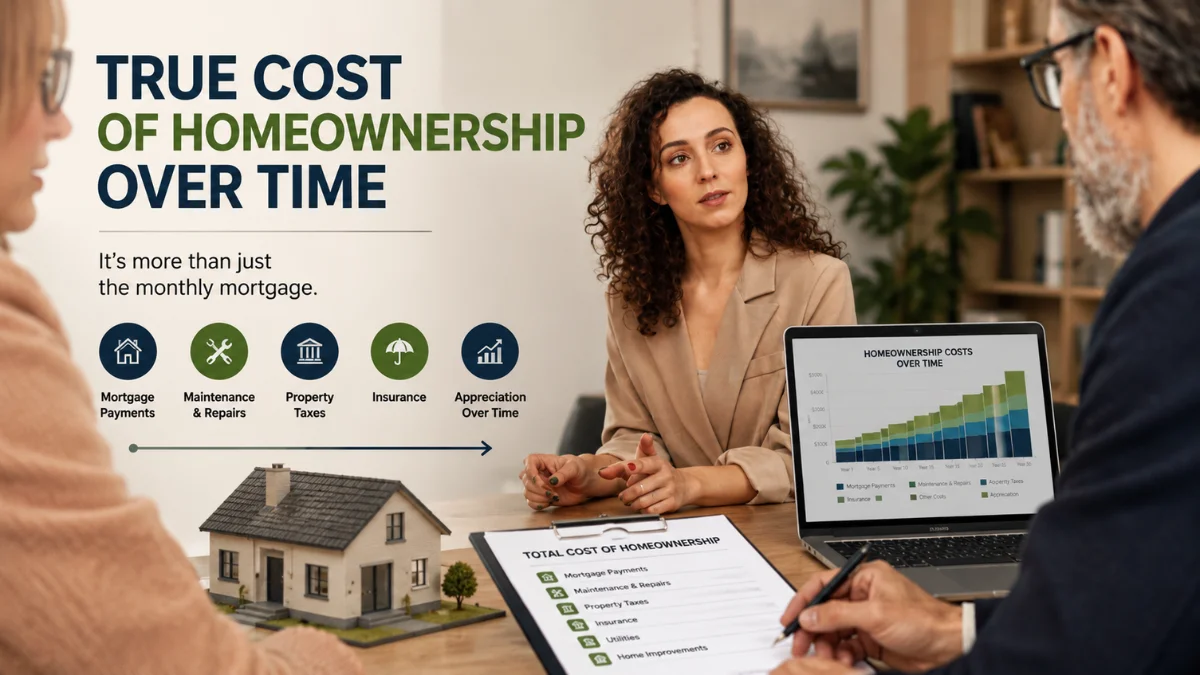
There’s also greater understanding of total ownership costs. Mortgage payments are only one part of the financial equation. Property taxes, insurance premiums, maintenance, and unexpected repairs can quickly increase overall housing expenses.
Lessons similar to hidden home buying costs I forgot to budget have encouraged buyers to factor in these realities before committing.
What to Read Next
Loan structure choices are reflecting this cautious mindset as well. Many buyers prefer stable, fixed-rate options over adjustable loans to reduce future payment uncertainty. This approach prioritizes predictability and long-term stability rather than short-term savings.
At the same time, buyers are thinking strategically about future flexibility. Many review options through the ultimate guide to refinancing your mortgage, understanding that refinancing could offer adjustments later but only if the original loan remains financially sustainable.
Lenders report that borrowers today ask more detailed questions about debt ratios, total interest paid, and repayment timelines. This suggests a shift toward disciplined borrowing rather than risk-taking.
Taking smaller mortgage risks does not signal hesitation, it reflects smarter financial planning. Buyers are aligning mortgage decisions with long-term stability, ensuring homeownership strengthens their financial future instead of creating unnecessary pressure.